Set your boundaries
Choose a comfortable monthly budget, available cash, must-haves, and a move date with room for delays.
 MKAT GROUPKELLER WILLIAMS SIGNATURE
KATY & WEST HOUSTON · NEW CONSTRUCTION
Before the model-home tour, build your buying plan.
Compare builders, understand the full cost, and plan the steps from your first visit to your final walkthrough with Katie Curran, REALTOR®.
Katy · Fulshear · Richmond · Cypress · Brookshire
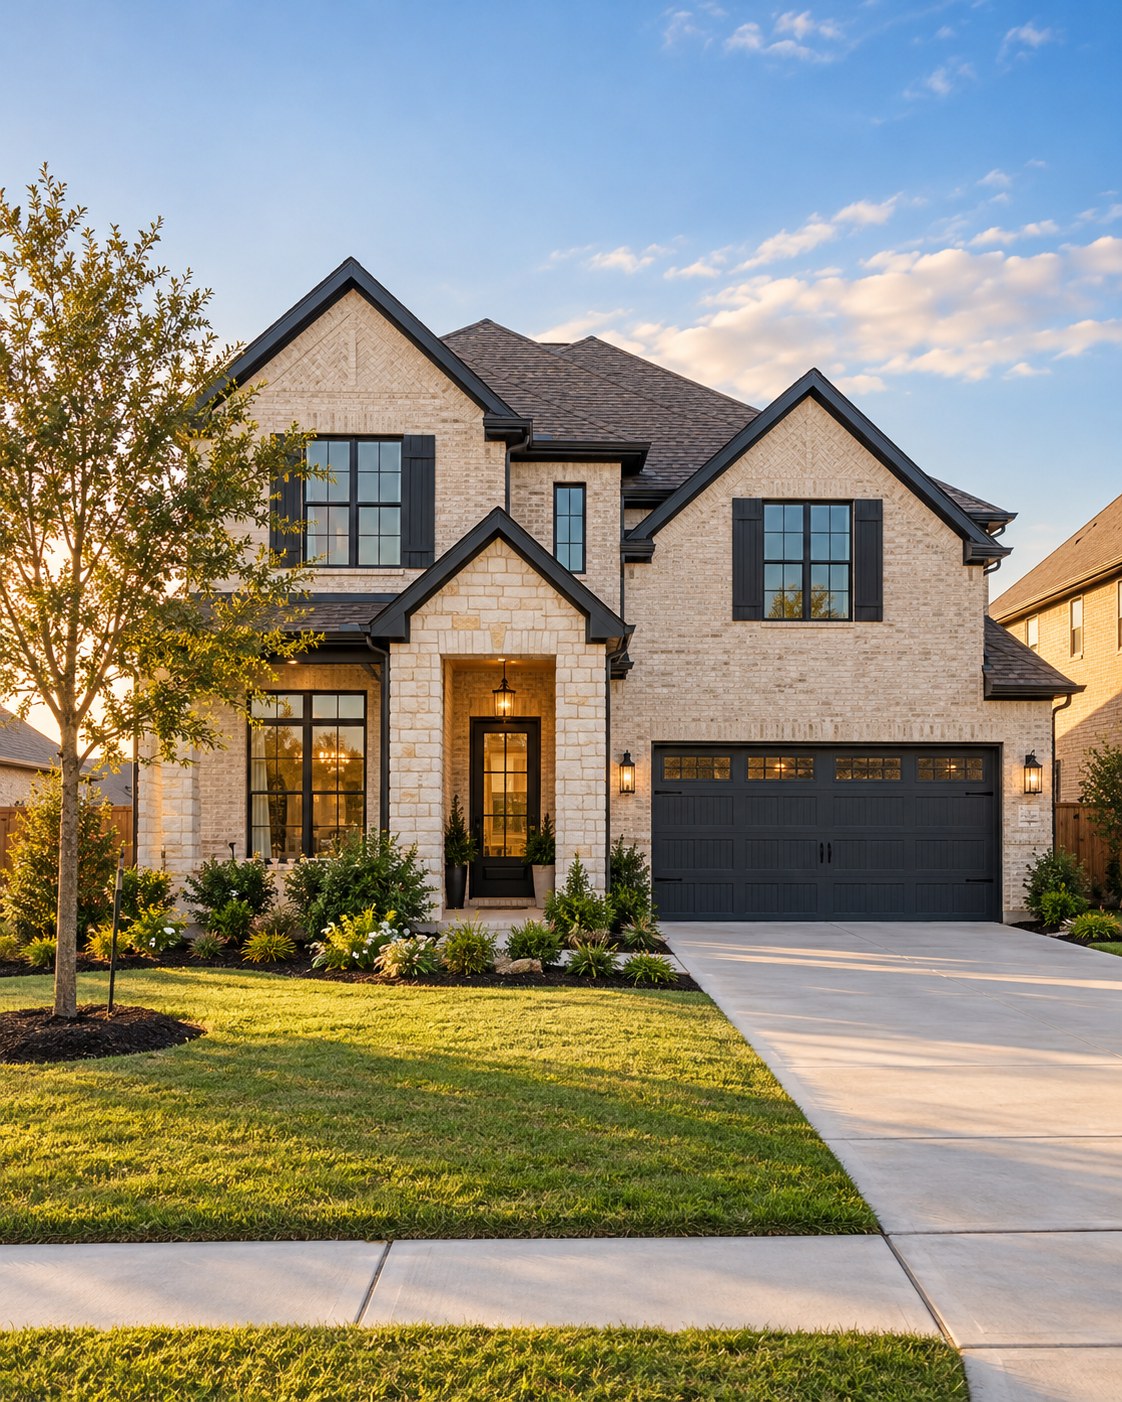
The floor plan is one decision. The contract, community, timeline, and complete cost deserve the same attention.
01 / START WITH YOUR INTERESTS
Make representation part of the first conversation.
Ask who the sales representative represents. If you want Katie to represent you, connect before an online registration or model-home visit so the builder’s registration requirements can be checked. If you have already visited, share when, where, and what you signed.
Review your written representation agreement, compensation, and any builder contribution. Do not assume representation costs you nothing or that every builder follows the same policy.
Discuss my first visit ↗See TREC’s 2026 buyer representation guidance for current written-agreement requirements.
Choose a comfortable monthly budget, available cash, must-haves, and a move date with room for delays.
Request the home price, lot premium, upgrades, eligible credits, lender conditions, and offer expiration in writing.
Compare a completed inventory home, a home still being built, and a suitable resale before committing.
02 / CHOOSE YOUR PATH
See the actual finishes and lot. Confirm readiness, inspection access, outstanding work, and the closing date.
Your next step: request the home-specific specification sheet and written offer.
Balance remaining selections against the work still ahead. An estimated finish date needs a backup plan.
Your next step: obtain the construction schedule and inspection-access terms.
More selection decisions can mean more deposits, upgrades, and time. Confirm what is included before choosing options.
Your next step: set an upgrade ceiling and review change-order rules.
Still deciding? Read Katie’s new construction versus resale guide. Its market figures reflect the article’s publication date.
03 / FROM FIRST QUESTIONS TO YOUR FIRST NIGHT
Decide what your move needs to solve. Write down your budget, location priorities, financing plan, and timing. Ask your lender which documents they need; send financial records only through their secure channel.
Decide which tradeoffs you can live with. Tour shortlisted homes and resale alternatives. Collect specifications, HOA documents, tax estimates, utility information, and written incentives for each address.
Decide whether the written terms work for you. Understand deposits, refund conditions, financing deadlines, delays, inspection access, selections, and warranty terms. Ask an attorney about legal interpretation or unfamiliar builder provisions; do not assume a standard option period applies.
Decide when independent reviews are needed. Confirm permitted inspection stages and notice requirements with the builder and inspector. Keep selection approvals, change orders, updates, and repair requests in writing.
Decide whether the closing requirements are satisfied. Coordinate your independent inspection and final walkthrough, document unresolved items, confirm lender and title requirements, and independently verify wire instructions using a trusted phone number.
Decide how you will protect your records and deadlines. Save warranty documents and manuals, calendar actual claim deadlines, confirm tax and exemption questions with the appraisal district, and keep maintenance records.
04 / BEFORE YOUR FIRST BUILDER VISIT
You do not need builder quotes or loan details to get started. Answer four quick questions for a preparation checklist and a useful first conversation with Katie.
Contact Katie before registering online or visiting a model home. She can help check the builder’s registration policy and discuss written representation and compensation terms. If you have already visited, let’s check your options before your next visit.
Plan My Builder Visits With Katie ↗Opens MKAT Group’s Wix contact page. Mention “New Construction Visit Plan.” No automatic booking or submission occurs here.
UNDERSTAND THE OFFER / SAVE THE MATH FOR A CONVERSATION
Builder incentives can work in different ways. You do not need to collect offers before reaching out—we can discuss what to ask before your first tour.
Example: a $400,000 home reduced by $10,000 has a $390,000 purchase price. That can reduce the loan amount; the payment also depends on your down payment and financing.
Upfront discount points can secure a lower fixed note rate for the life of that loan. The lender must quote the cost and resulting rate; a builder credit does not translate into a fixed rate reduction.
A funded subsidy lowers your share of the mortgage payment for the first two years. Your payment steps up to the full note-rate amount in year three; the loan’s note rate does not change.
The useful question: which option fits your cash needs, comfortable ongoing payment, and expected time keeping the loan? Katie can help organize the comparison with your lender once you have real written offers.
Illustrative education, not a current builder offer or loan quote. Taxes, insurance, HOA dues, loan fees, eligibility, and incentive restrictions also matter.
05 / YOUR NEXT CONVERSATION
Check what you have confirmed. This checklist stays on this page only; it does not send information to MKAT Group.
0 of 8 confirmed
06 / FIND YOUR PART OF WEST HOUSTON
Use these local guides to begin your shortlist. Confirm current availability with each builder and verify taxes, school assignments, flood information, and restrictions for the exact parcel.
Compare the exact address, commute route, tax district, and school assignment rather than treating every Katy mailing address as the same market.
Katy area guide ↗Compare build stages, lot premiums, HOA documents, and amenities already open against those still planned.
Fulshear area guide ↗Check the specific parcel’s county, taxing units, and school district. Use the Austin Point article below as one starting point, not a live inventory feed.
Richmond area guide ↗Test your daily route and compare construction activity, drainage information, and the costs of each specific home.
Cypress area guide ↗Review access to your regular destinations, utility providers, district taxes, and future construction near the homesite.
Brookshire area guide ↗07 / GO A LITTLE DEEPER
Selected MKAT Group articles. Prices, incentives, school assignments, and market figures in older posts require fresh confirmation.
Prepare questions before your first model-home visit.
Compare the community as carefully as the floor plan.
Weigh both buying paths before choosing one.
Explore a specific Richmond-area community.
Look beyond the city name when comparing costs.
08 / QUESTIONS BEFORE YOU COMMIT
You can buy directly from a builder. If you want your own representation, speak with Katie before touring or registering online. Confirm the sales representative’s role, the builder’s registration policy, and your written representation and compensation terms before proceeding.
No universal payment arrangement applies. Compensation is negotiable. Review your written agreement, any builder contribution, and any amount you may owe before committing.
Compare written Loan Estimates for the same loan type and lock period. Check rate, points, fees, cash to close, and the conditions on any builder credit. Ask what happens to the incentive if you choose another lender or closing is delayed.
Consider an independent inspection even when the home is new. Discuss access, timing, scope, and reporting with a licensed inspector and the builder before signing. A builder walkthrough and an independent inspection serve different purposes.
Do not assume so. Ask the appraisal district and lender whether the estimate reflects the completed home and all taxing units. Confirm exemptions separately; a land-only or partially completed assessment is not a reliable ongoing budget.
The answer depends on the specific home, construction stage, permits, materials, weather, and contract. Get the builder’s estimated completion date and delay provisions in writing, and keep a backup housing plan.
You can ask about price, eligible credits, lot premiums, upgrades, and closing terms. Availability and flexibility vary. Request the complete offer in writing and compare the total cost rather than assuming a headline incentive is the best value.
Keep your contract, warranty, inspection reports, repair records, and equipment manuals together. Calendar the actual warranty deadlines in your documents, use the required claim process, and address maintenance requirements.
YOUR LOCAL REAL ESTATE ADVISOR
MKAT Group | Keller Williams Signature
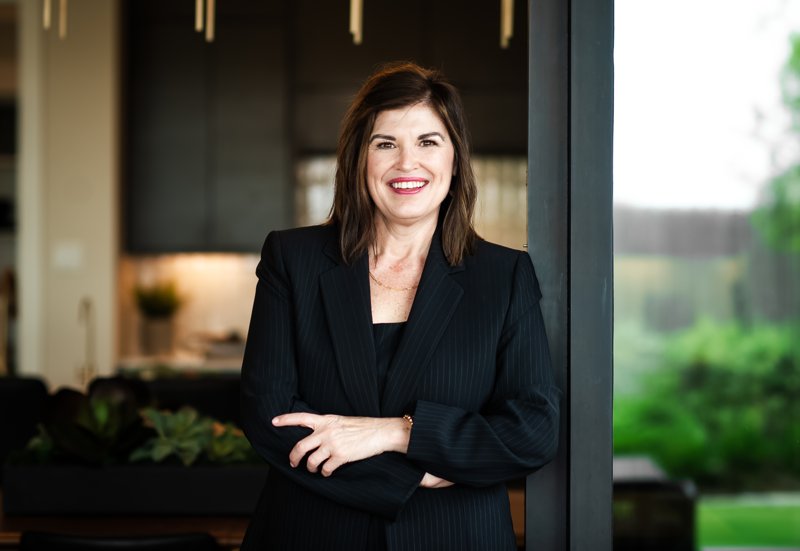
Katie is co-founder of MKAT Group and serves buyers and sellers across Katy, Fulshear, Richmond, Cypress, Brookshire, and Greater Houston. She helps buyers compare homes and communities, evaluate the real estate terms of an offer, and coordinate the steps toward closing.
This guide is by Katie Curran. Reviewed October 18, 2026. Educational information; obtain property-specific lending, inspection, legal, tax, and insurance advice from the appropriate professional.
Meet Katie & MKAT Group ↗A THOUGHTFUL FIRST STEP
Share your target area, timing, and the communities you are considering through our Wix contact page. Mention “New Construction” and whether you have already visited or registered with a builder. Katie can discuss the next steps with you.
Contact requests open MKAT Group’s existing Wix form. Please do not send sensitive financial documents here.